
ICEUPWRT · ICE U.S. Electricity Futures Index Monthly Index Update
As of October 31, 2026 Index-level reporting · fund pending launch
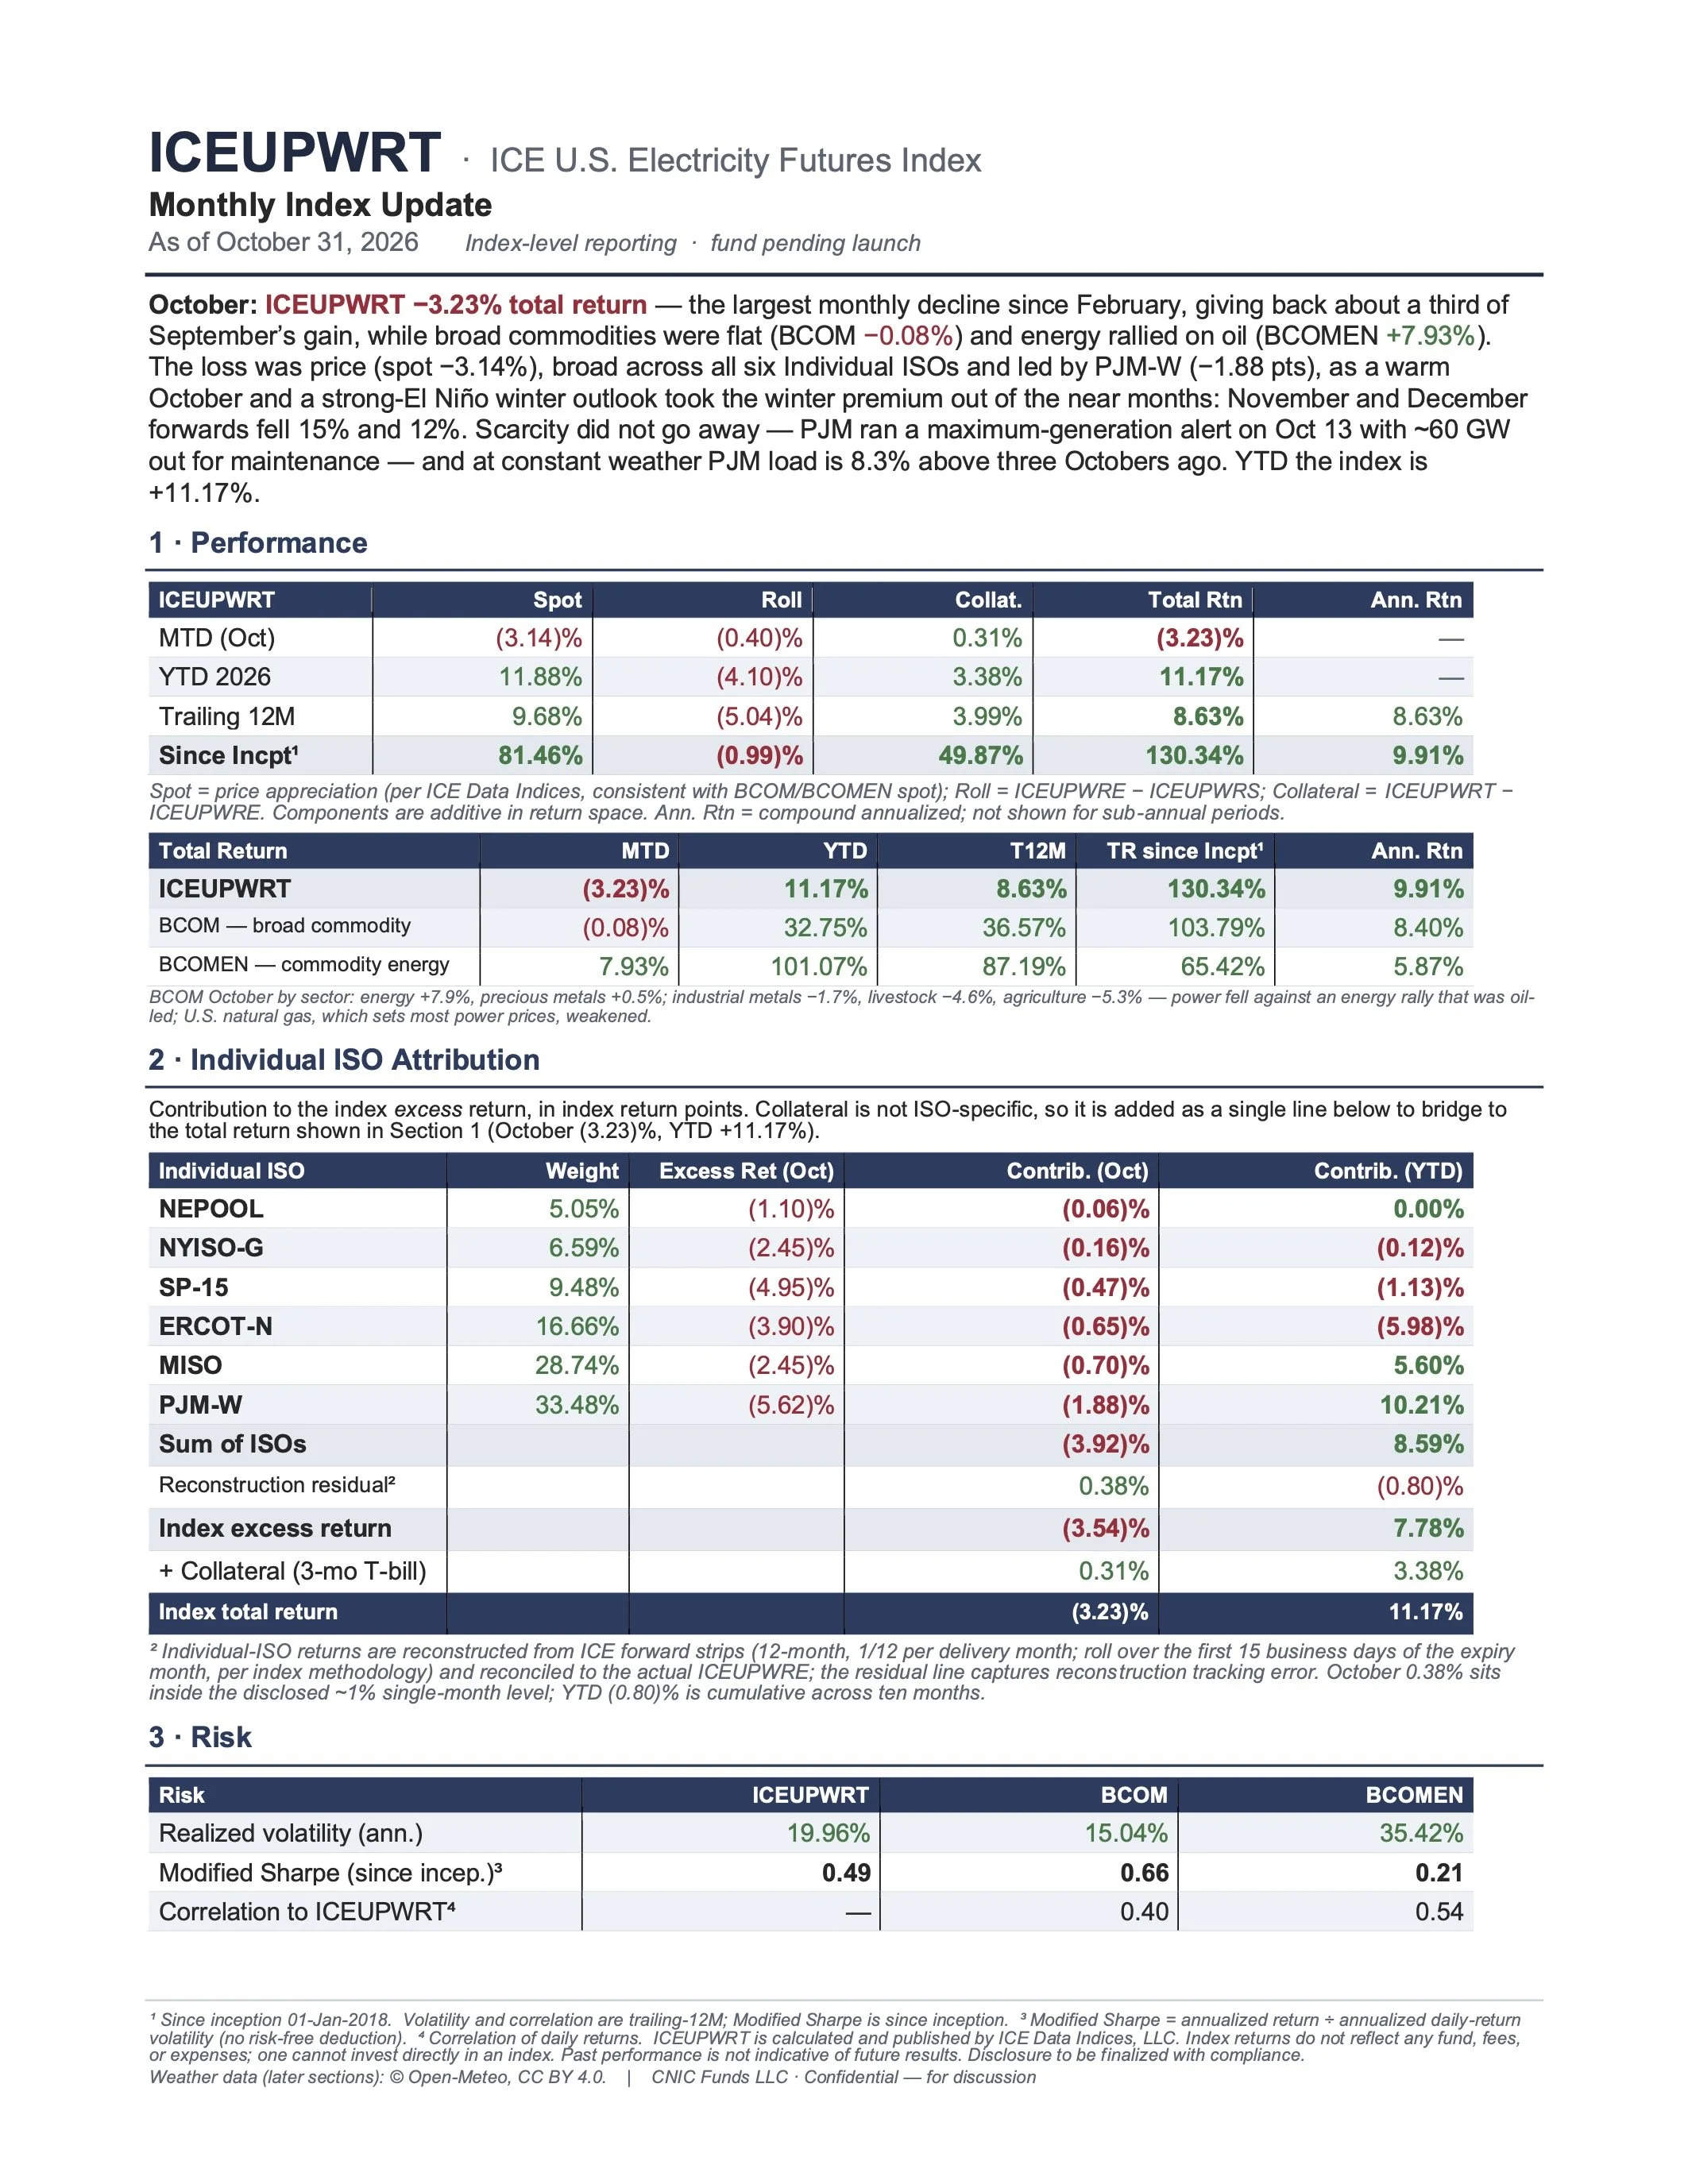
October: ICEUPWRT −3.23% total return — the largest monthly decline since February, giving back about a third of September’s gain, while broad commodities were flat (BCOM −0.08%) and energy rallied on oil (BCOMEN +7.93%). The loss was price (spot −3.14%), broad across all six Individual ISOs and led by PJM-W (−1.88 pts), as a warm October and a strong-El Niño winter outlook took the winter premium out of the near months: November and December forwards fell 15% and 12%. Scarcity did not go away — PJM ran a maximum-generation alert on Oct 13 with ~60 GW out for maintenance — and at constant weather PJM load is 8.3% above three Octobers ago. YTD the index is +11.17%.
1 · Performance
MTD (Oct) (3.14)% (0.40)% 0.31% (3.23)% — Trailing 12M 9.68% (5.04)% 3.99% 8.63% 8.63%
Spot = price appreciation (per ICE Data Indices, consistent with BCOM/BCOMEN spot); Roll = ICEUPWRE − ICEUPWRS; Collateral = ICEUPWRT − ICEUPWRE. Components are additive in return space. Ann. Rtn = compound annualized; not shown for sub-annual periods.
ICEUPWRT
Spot
Roll
Collat.
Total Rtn
Ann. Rtn
YTD 2026
11.88%
(4.10)%
3.38%
11.17%
—
Since Incpt1
81.46%
(0.99)%
49.87%
130.34%
9.91%
Total Return
MTD
YTD
T12M
TR since Incpt1
Ann. Rtn
ICEUPWRT
(3.23)%
11.17%
8.63%
130.34%
9.91%
BCOM — broad commodity
(0.08)%
32.75%
36.57%
103.79%
8.40%
BCOMEN — commodity energy
7.93% 101.07% 87.19% 65.42% 5.87%
BCOM October by sector: energy +7.9%, precious metals +0.5%; industrial metals −1.7%, livestock −4.6%, agriculture −5.3% — power fell against an energy rally that was oil- led; U.S. natural gas, which sets most power prices, weakened.
2 · Individual ISO Attribution
Contribution to the index excess return, in index return points. Collateral is not ISO-specific, so it is added as a single line below to bridge to the total return shown in Section 1 (October (3.23)%, YTD +11.17%).
Individual ISO
Weight
Excess Ret (Oct)
Contrib. (Oct)
Contrib. (YTD)
NEPOOL 5.05% (1.10)% (0.06)% SP-15 9.48% (4.95)% (0.47)% MISO 28.74% (2.45)% (0.70)%
Reconstruction residual2 0.38% + Collateral (3-mo T-bill) 0.31%
0.00%
(1.13)%
5.60%
(0.80)%
3.38%
NYISO-G
6.59%
(2.45)%
(0.16)%
(0.12)%
ERCOT-N
16.66%
(3.90)%
(0.65)%
(5.98)%
PJM-W
33.48%
(5.62)%
(1.88)%
10.21%
Sum of ISOs
(3.92)%
8.59%
Index excess return
(3.54)%
7.78%
Index total return
(3.23)%
11.17%
2 Individual-ISO returns are reconstructed from ICE forward strips (12-month, 1/12 per delivery month; roll over the first 15 business days of the expiry month, per index methodology) and reconciled to the actual ICEUPWRE; the residual line captures reconstruction tracking error. October 0.38% sits inside the disclosed ~1% single-month level; YTD (0.80)% is cumulative across ten months.
3 · Risk
Modified Sharpe (since incep.)3 0.49 0.66 0.21
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
Risk
ICEUPWRT
BCOM
BCOMEN
Realized volatility (ann.)
19.96%
15.04%
35.42%
Correlation to ICEUPWRT4
—
0.40
0.54
ICEUPWRT · Monthly Index Update · October 31, 2026 4 · Daily Prices & Real-Time Spikes
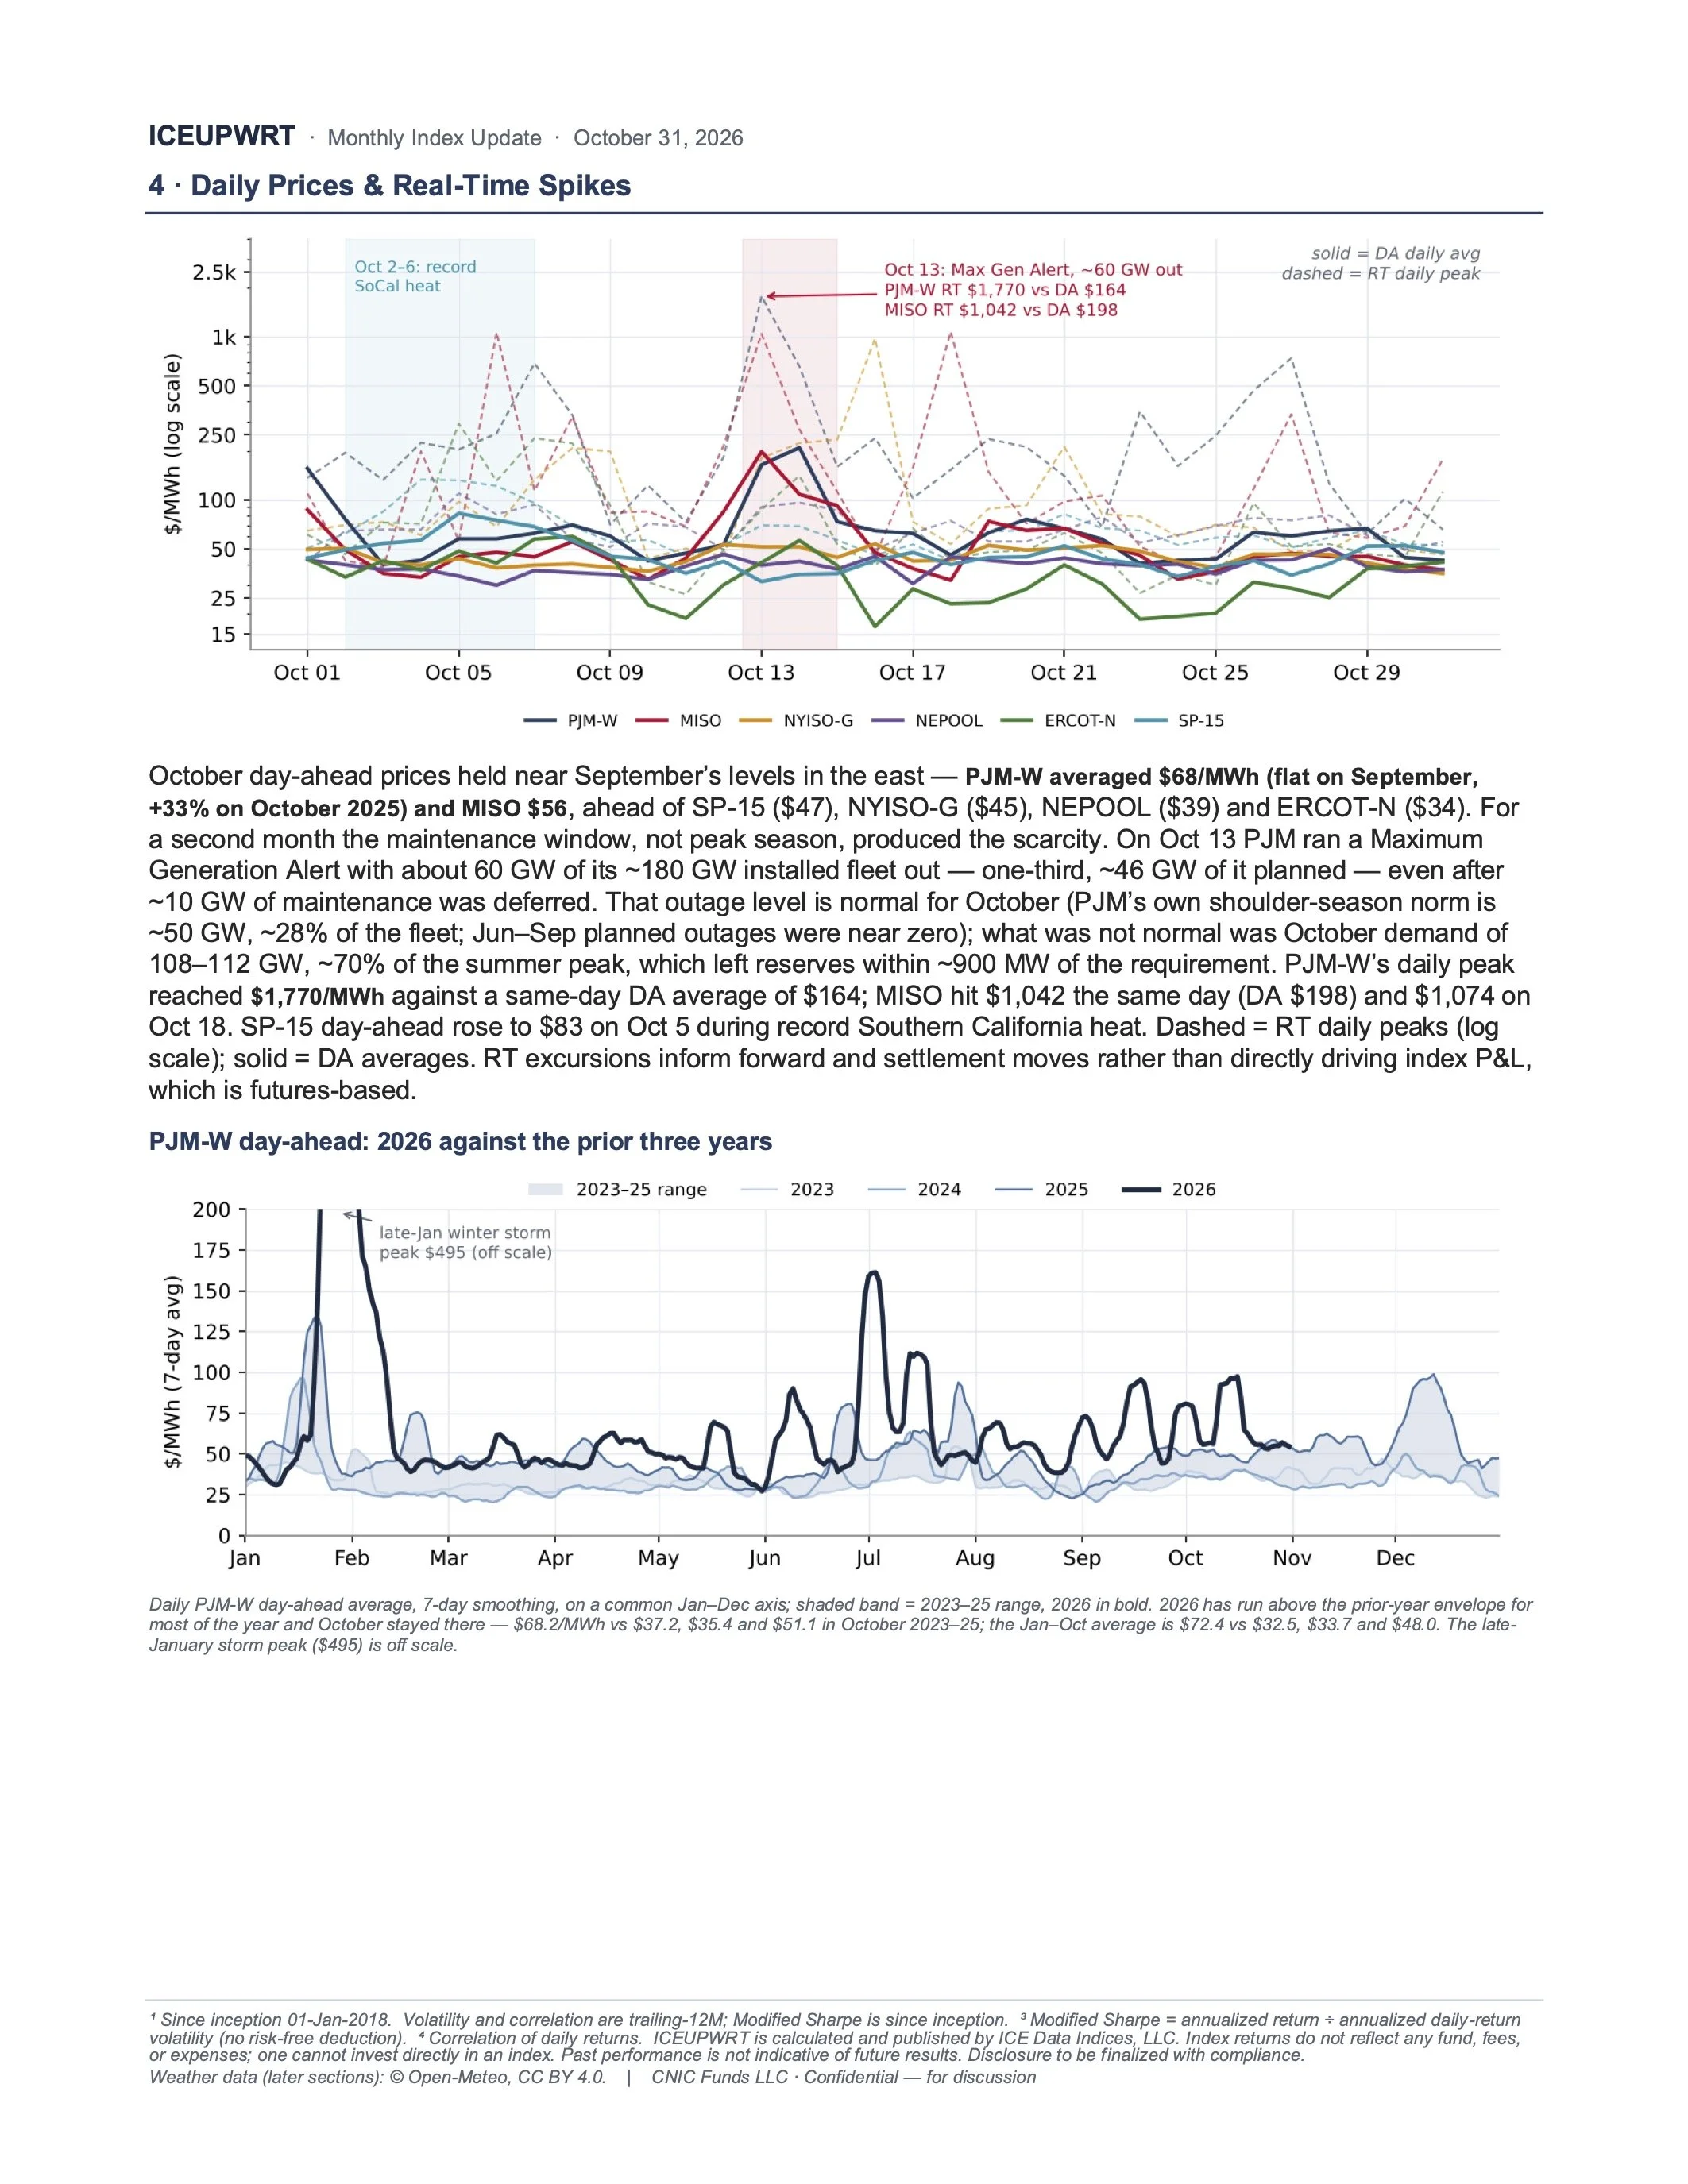
October day-ahead prices held near September’s levels in the east — PJM-W averaged $68/MWh (flat on September, +33% on October 2025) and MISO $56, ahead of SP-15 ($47), NYISO-G ($45), NEPOOL ($39) and ERCOT-N ($34). For a second month the maintenance window, not peak season, produced the scarcity. On Oct 13 PJM ran a Maximum Generation Alert with about 60 GW of its ~180 GW installed fleet out — one-third, ~46 GW of it planned — even after ~10 GW of maintenance was deferred. That outage level is normal for October (PJM’s own shoulder-season norm is ~50 GW, ~28% of the fleet; Jun–Sep planned outages were near zero); what was not normal was October demand of 108–112 GW, ~70% of the summer peak, which left reserves within ~900 MW of the requirement. PJM-W’s daily peak reached $1,770/MWh against a same-day DA average of $164; MISO hit $1,042 the same day (DA $198) and $1,074 on Oct 18. SP-15 day-ahead rose to $83 on Oct 5 during record Southern California heat. Dashed = RT daily peaks (log scale); solid = DA averages. RT excursions inform forward and settlement moves rather than directly driving index P&L, which is futures-based.
PJM-W day-ahead: 2026 against the prior three years
Daily PJM-W day-ahead average, 7-day smoothing, on a common Jan–Dec axis; shaded band = 2023–25 range, 2026 in bold. 2026 has run above the prior-year envelope for most of the year and October stayed there — $68.2/MWh vs $37.2, $35.4 and $51.1 in October 2023–25; the Jan–Oct average is $72.4 vs $32.5, $33.7 and $48.0. The late- January storm peak ($495) is off scale.
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
ICEUPWRT · Monthly Index Update · October 31, 2026 5 · Weather: Heating & Cooling Demand
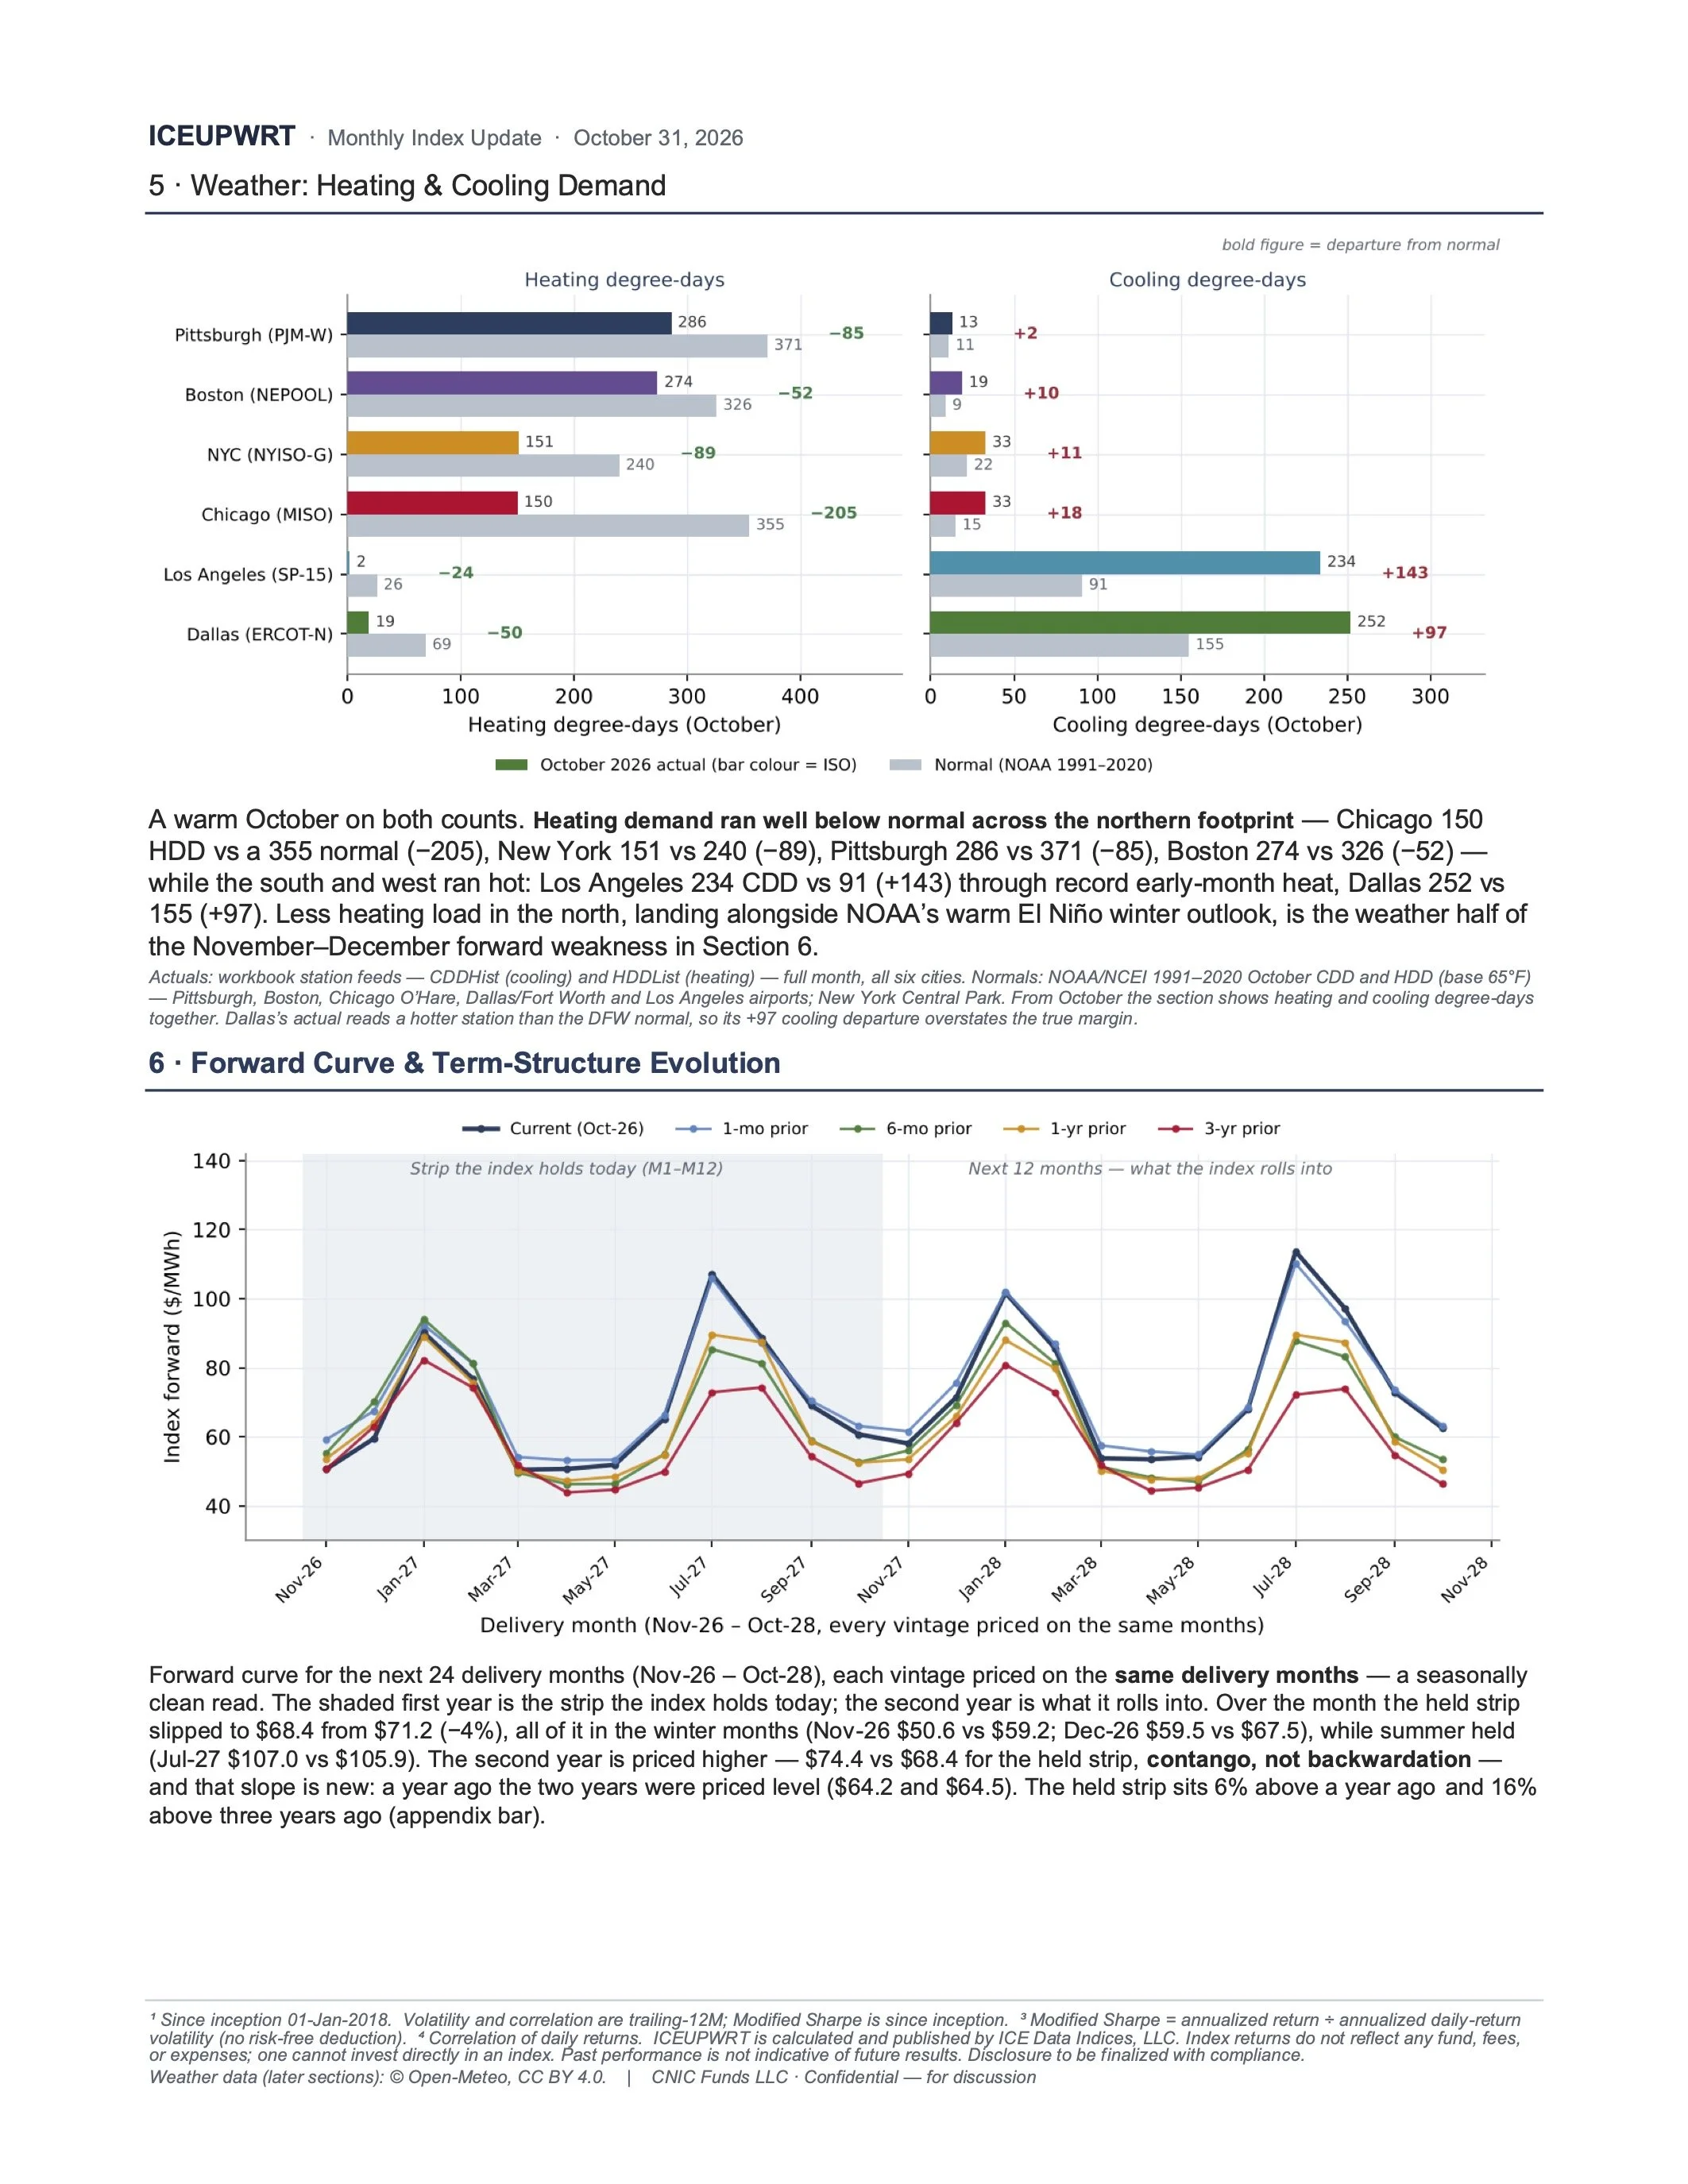
A warm October on both counts. Heating demand ran well below normal across the northern footprint — Chicago 150 HDD vs a 355 normal (−205), New York 151 vs 240 (−89), Pittsburgh 286 vs 371 (−85), Boston 274 vs 326 (−52) — while the south and west ran hot: Los Angeles 234 CDD vs 91 (+143) through record early-month heat, Dallas 252 vs 155 (+97). Less heating load in the north, landing alongside NOAA’s warm El Niño winter outlook, is the weather half of the November–December forward weakness in Section 6.
Actuals: workbook station feeds — CDDHist (cooling) and HDDList (heating) — full month, all six cities. Normals: NOAA/NCEI 1991–2020 October CDD and HDD (base 65°F) — Pittsburgh, Boston, Chicago O’Hare, Dallas/Fort Worth and Los Angeles airports; New York Central Park. From October the section shows heating and cooling degree-days together. Dallas’s actual reads a hotter station than the DFW normal, so its +97 cooling departure overstates the true margin.
6 · Forward Curve & Term-Structure Evolution
Forward curve for the next 24 delivery months (Nov-26 – Oct-28), each vintage priced on the same delivery months — a seasonally clean read. The shaded first year is the strip the index holds today; the second year is what it rolls into. Over the month t he held strip slipped to $68.4 from $71.2 (−4%), all of it in the winter months (Nov-26 $50.6 vs $59.2; Dec-26 $59.5 vs $67.5), while summer held (Jul-27 $107.0 vs $105.9). The second year is priced higher — $74.4 vs $68.4 for the held strip, contango, not backwardation — and that slope is new: a year ago the two years were priced level ($64.2 and $64.5). The held strip sits 6% above a year ago and 16% above three years ago (appendix bar).
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
ICEUPWRT · Monthly Index Update · October 31, 2026
7 · News & Commentary
Key events
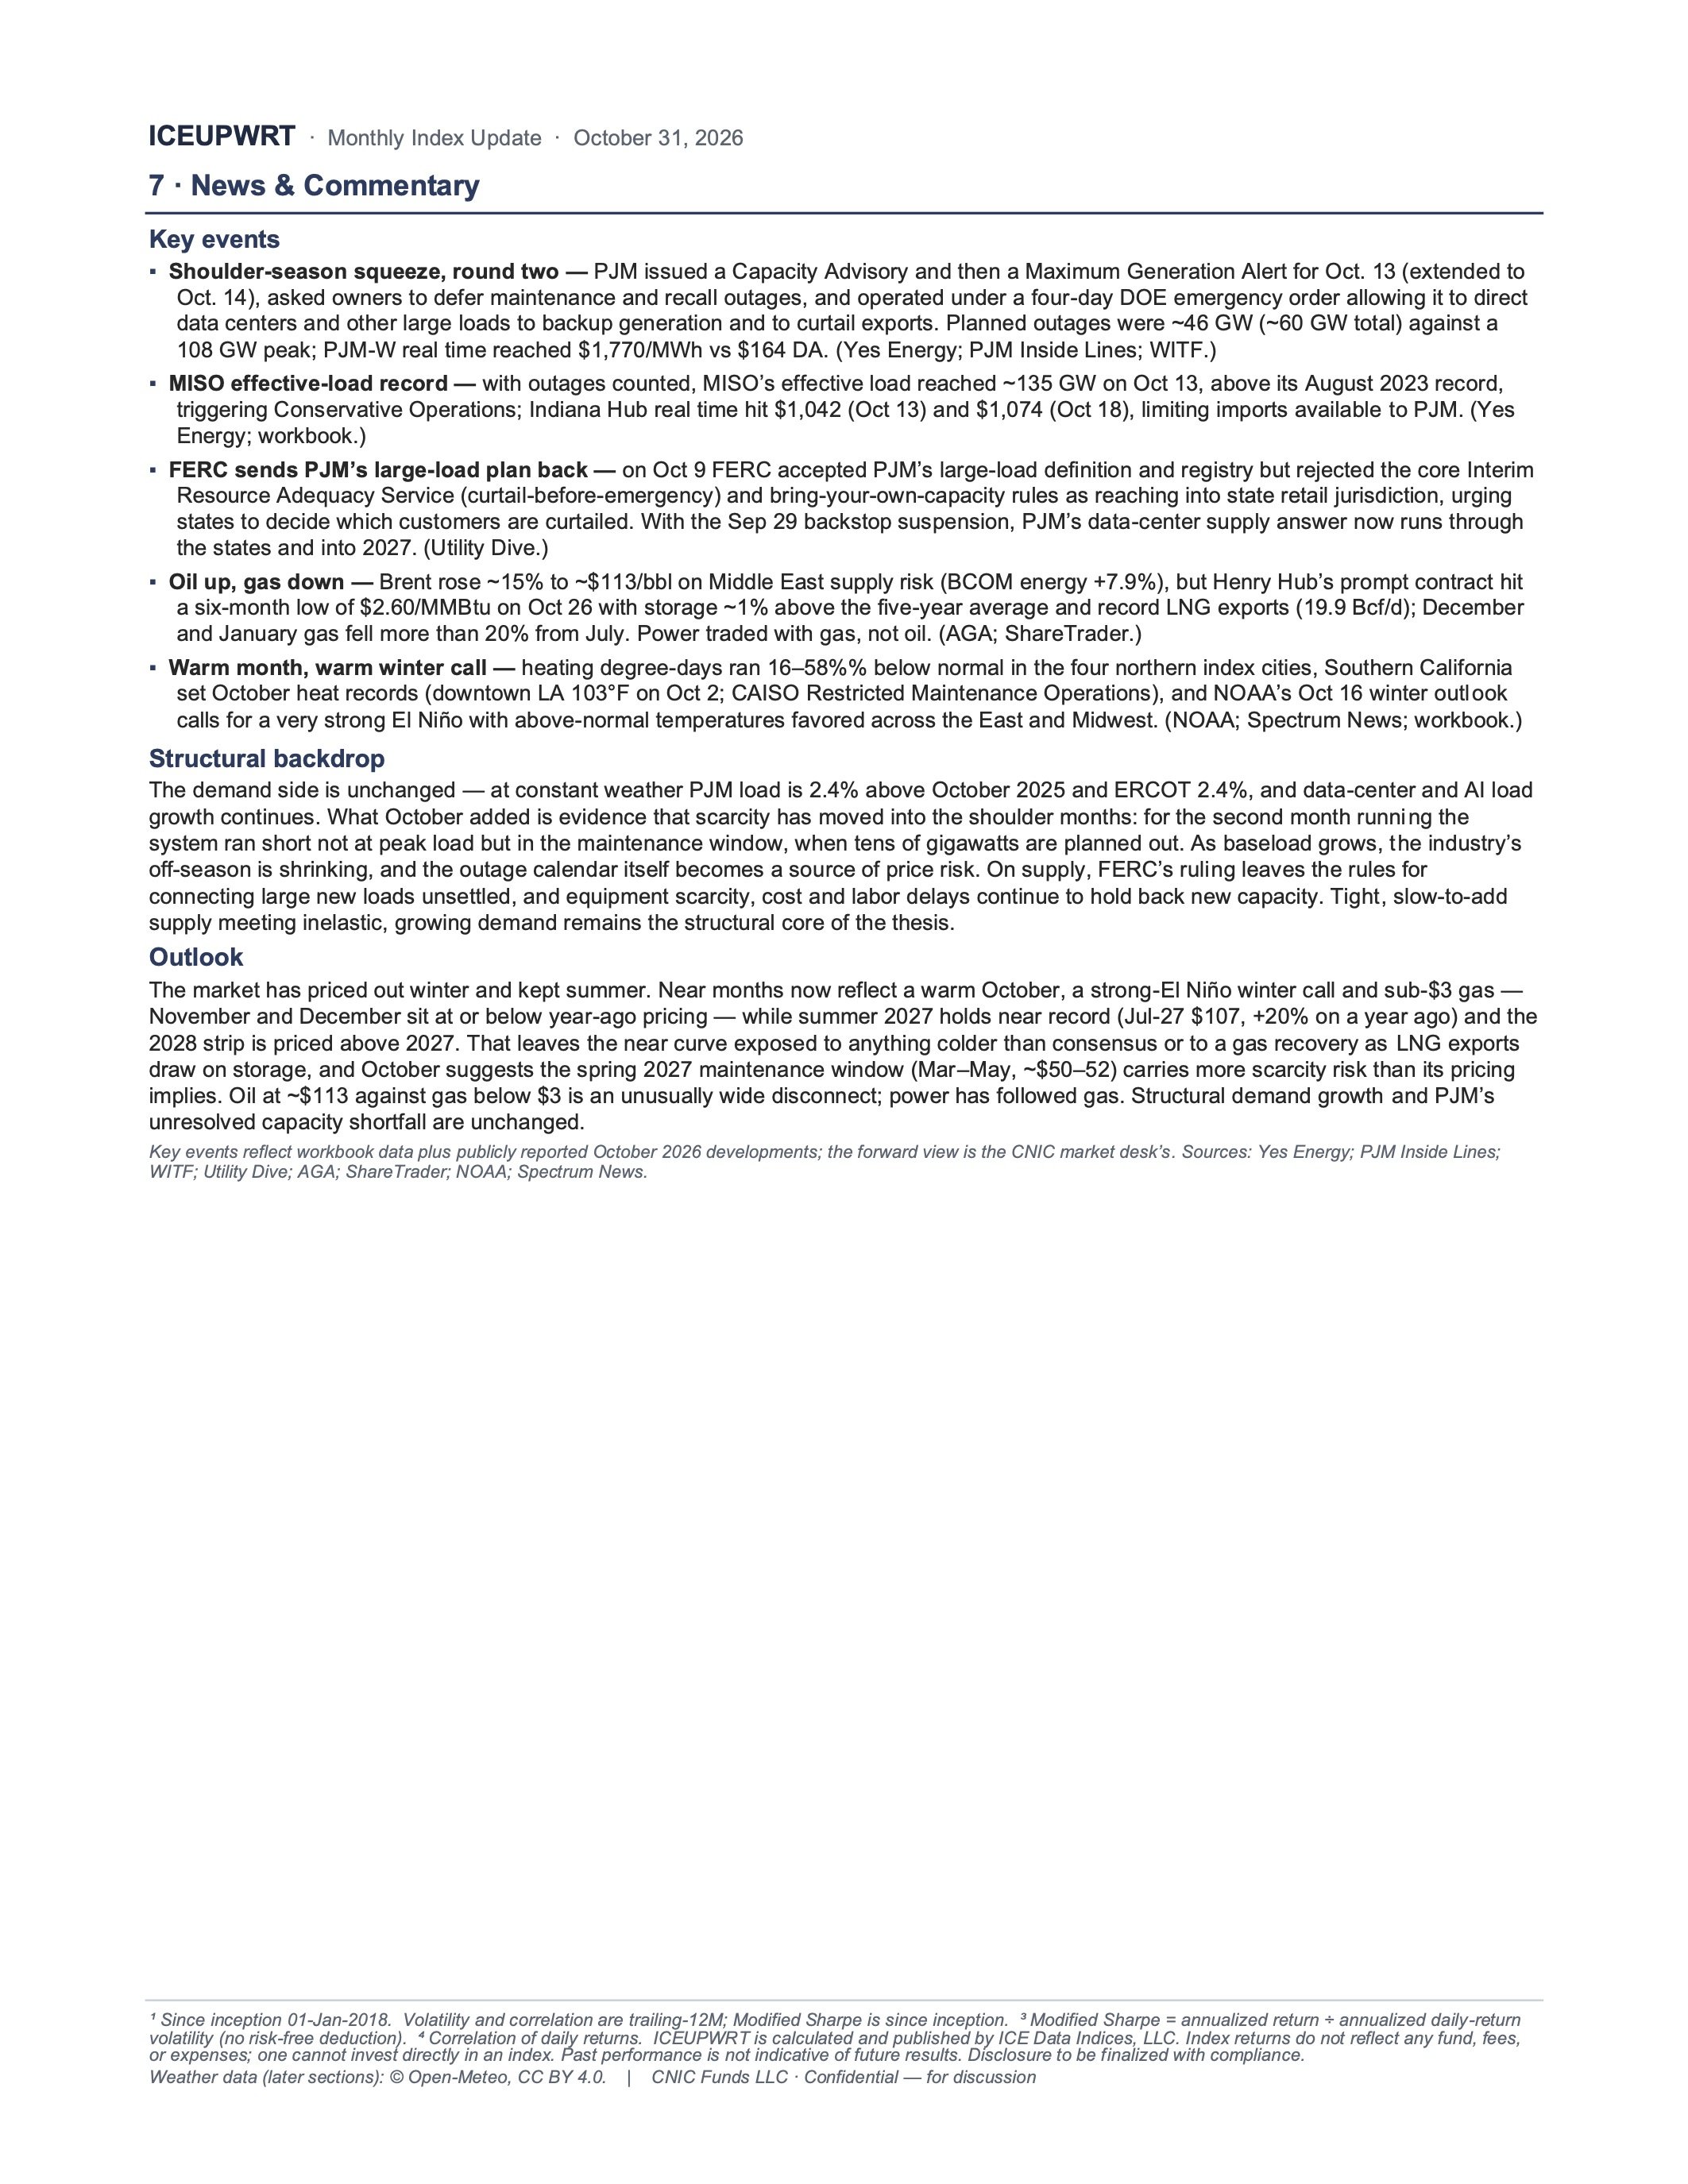
▪ Shoulder-season squeeze, round two — PJM issued a Capacity Advisory and then a Maximum Generation Alert for Oct. 13 (extended to Oct. 14), asked owners to defer maintenance and recall outages, and operated under a four-day DOE emergency order allowing it to direct data centers and other large loads to backup generation and to curtail exports. Planned outages were ~46 GW (~60 GW total) against a 108 GW peak; PJM-W real time reached $1,770/MWh vs $164 DA. (Yes Energy; PJM Inside Lines; WITF.)
▪ MISO effective-load record — with outages counted, MISO’s effective load reached ~135 GW on Oct 13, above its August 2023 record, triggering Conservative Operations; Indiana Hub real time hit $1,042 (Oct 13) and $1,074 (Oct 18), limiting imports available to PJM. (Yes Energy; workbook.)
▪ FERC sends PJM’s large-load plan back — on Oct 9 FERC accepted PJM’s large-load definition and registry but rejected the core Interim Resource Adequacy Service (curtail-before-emergency) and bring-your-own-capacity rules as reaching into state retail jurisdiction, urging states to decide which customers are curtailed. With the Sep 29 backstop suspension, PJM’s data-center supply answer now runs through the states and into 2027. (Utility Dive.)
▪ Oil up, gas down — Brent rose ~15% to ~$113/bbl on Middle East supply risk (BCOM energy +7.9%), but Henry Hub’s prompt contract hit a six-month low of $2.60/MMBtu on Oct 26 with storage ~1% above the five-year average and record LNG exports (19.9 Bcf/d); December and January gas fell more than 20% from July. Power traded with gas, not oil. (AGA; ShareTrader.)
▪ Warm month, warm winter call — heating degree-days ran 16–58%% below normal in the four northern index cities, Southern California set October heat records (downtown LA 103°F on Oct 2; CAISO Restricted Maintenance Operations), and NOAA’s Oct 16 winter outlook calls for a very strong El Niño with above-normal temperatures favored across the East and Midwest. (NOAA; Spectrum News; workbook.)
Structural backdrop
The demand side is unchanged — at constant weather PJM load is 2.4% above October 2025 and ERCOT 2.4%, and data-center and AI load growth continues. What October added is evidence that scarcity has moved into the shoulder months: for the second month running the system ran short not at peak load but in the maintenance window, when tens of gigawatts are planned out. As baseload grows, the industry’s off-season is shrinking, and the outage calendar itself becomes a source of price risk. On supply, FERC’s ruling leaves the rules for connecting large new loads unsettled, and equipment scarcity, cost and labor delays continue to hold back new capacity. Tight, slow-to-add supply meeting inelastic, growing demand remains the structural core of the thesis.
Outlook
The market has priced out winter and kept summer. Near months now reflect a warm October, a strong-El Niño winter call and sub-$3 gas — November and December sit at or below year-ago pricing — while summer 2027 holds near record (Jul-27 $107, +20% on a year ago) and the 2028 strip is priced above 2027. That leaves the near curve exposed to anything colder than consensus or to a gas recovery as LNG exports draw on storage, and October suggests the spring 2027 maintenance window (Mar–May, ~$50–52) carries more scarcity risk than its pricing implies. Oil at ~$113 against gas below $3 is an unusually wide disconnect; power has followed gas. Structural demand growth and PJM’s unresolved capacity shortfall are unchanged.
Key events reflect workbook data plus publicly reported October 2026 developments; the forward view is the CNIC market desk’s. Sources: Yes Energy; PJM Inside Lines; WITF; Utility Dive; AGA; ShareTrader; NOAA; Spectrum News.
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
ICEUPWRT · Monthly Index Update · October 31, 2026
8 · Weather-Normalized Load & Price
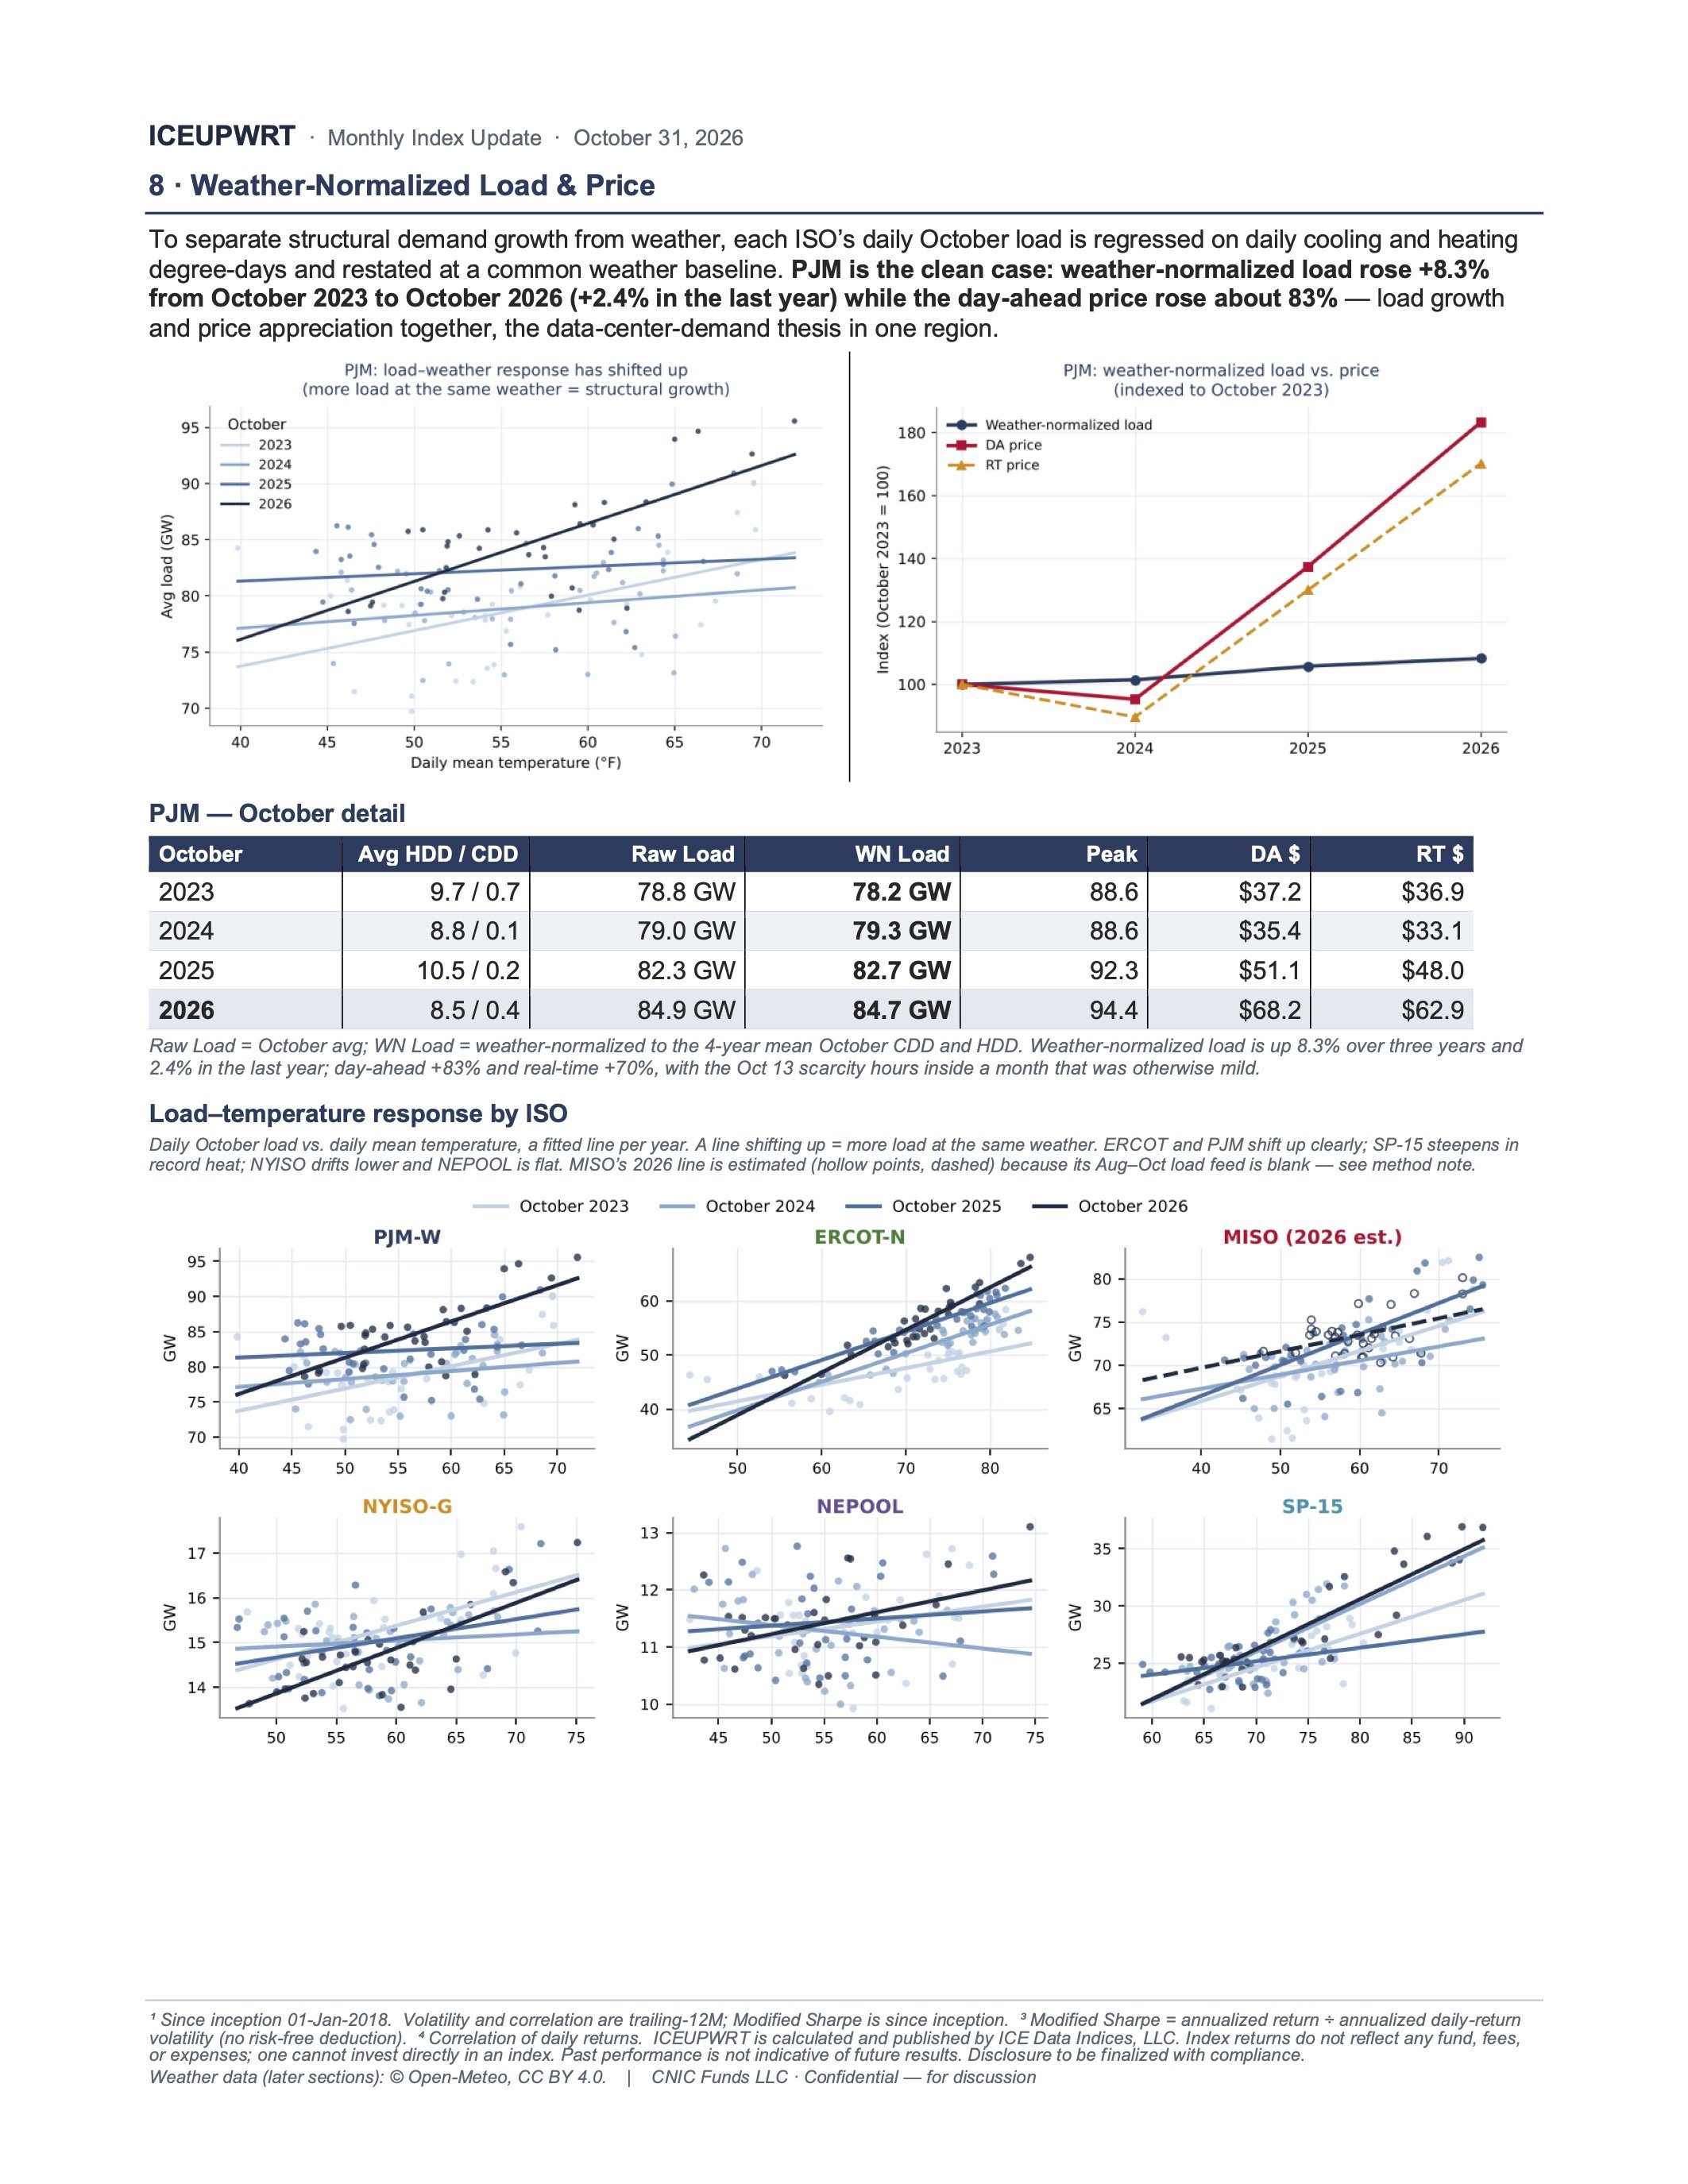
To separate structural demand growth from weather, each ISO’s daily October load is regressed on daily cooling and heating degree-days and restated at a common weather baseline. PJM is the clean case: weather-normalized load rose +8.3% from October 2023 to October 2026 (+2.4% in the last year) while the day-ahead price rose about 83% — load growth and price appreciation together, the data-center-demand thesis in one region.
PJM — October detail
2023 9.7 / 0.7 78.8 GW 78.2 GW 88.6 $37.2 $36.9
2025 10.5 / 0.2 82.3 GW 82.7 GW 92.3 $51.1 $48.0
Raw Load = October avg; WN Load = weather-normalized to the 4-year mean October CDD and HDD. Weather-normalized load is up 8.3% over three years and
2.4% in the last year; day-ahead +83% and real-time +70%, with the Oct 13 scarcity hours inside a month that was otherwise mild.
Load–temperature response by ISO
Daily October load vs. daily mean temperature, a fitted line per year. A line shifting up = more load at the same weather. ERCOT and PJM shift up clearly; SP-15 steepens in record heat; NYISO drifts lower and NEPOOL is flat. MISO’s 2026 line is estimated (hollow points, dashed) because its Aug–Oct load feed is blank — see method note.
October
Avg HDD / CDD
Raw Load
WN Load
Peak
DA $
RT $
2024
8.8 / 0.1
79.0 GW
79.3 GW
88.6
$35.4
$33.1
2026
8.5 / 0.4
84.9 GW
84.7 GW
94.4
$68.2
$62.9
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
Cross-ISO summary
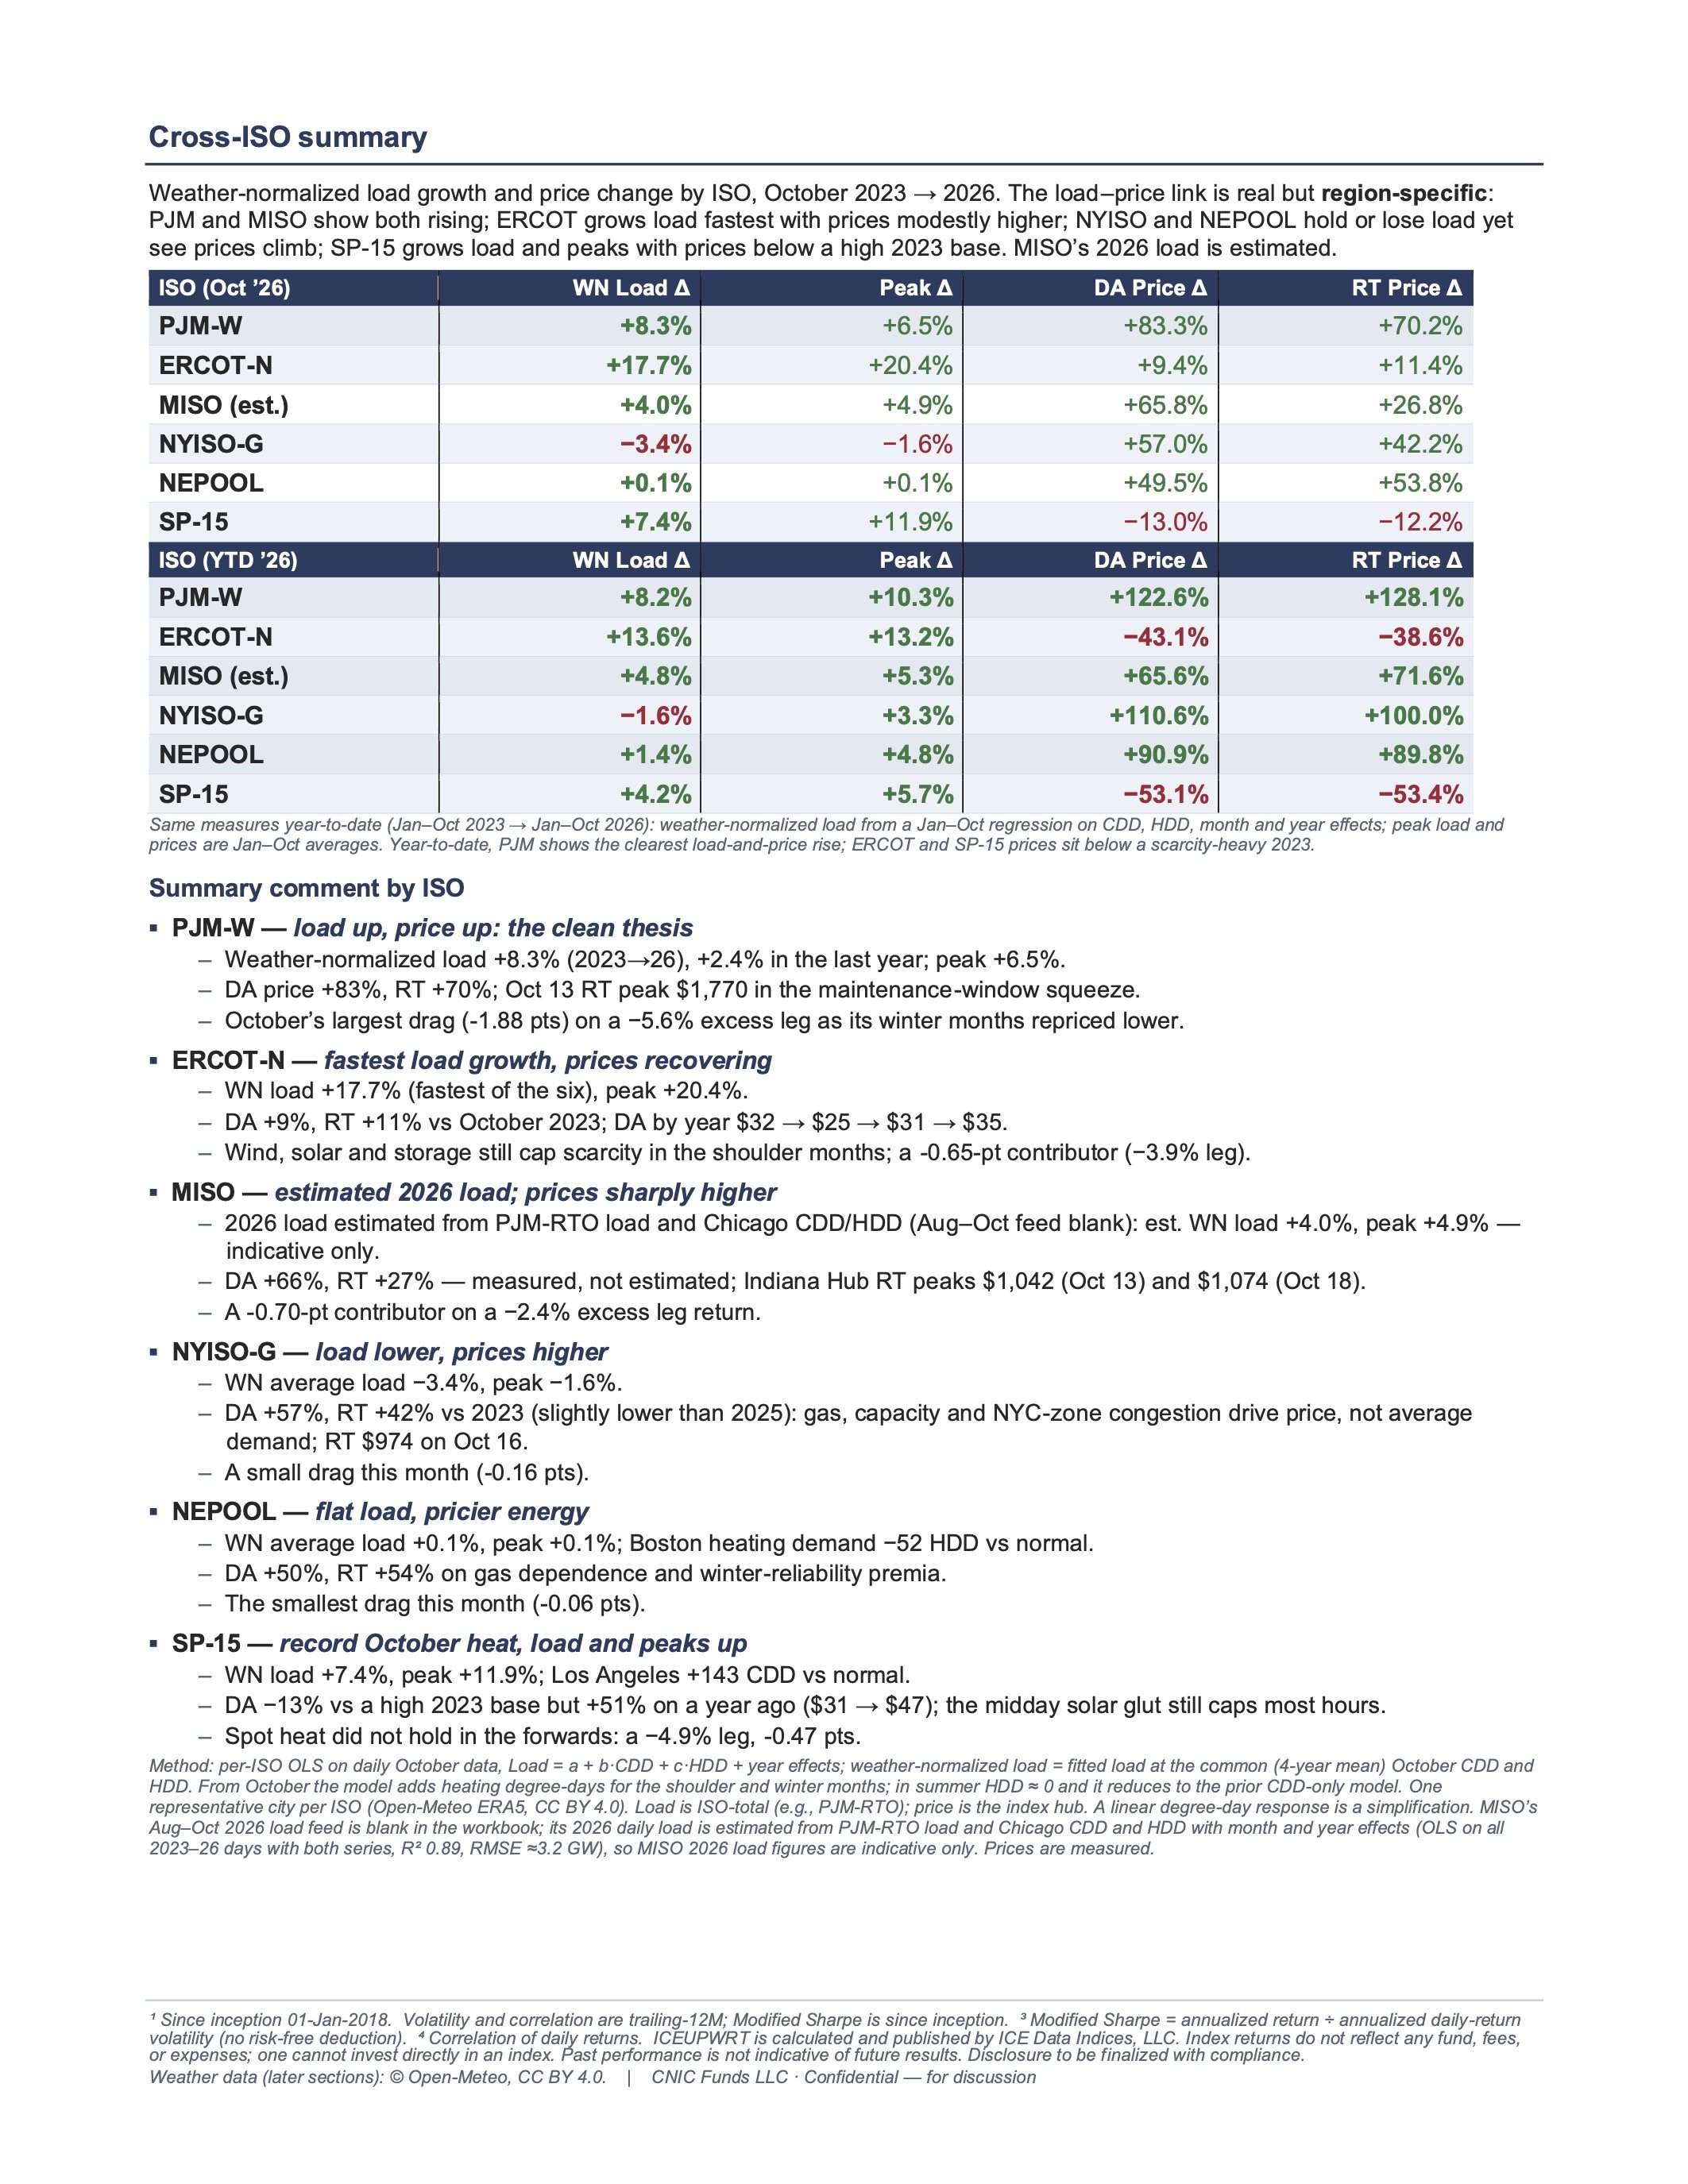
Weather-normalized load growth and price change by ISO, October 2023 → 2026. The load–price link is real but region-specific: PJM and MISO show both rising; ERCOT grows load fastest with prices modestly higher; NYISO and NEPOOL hold or lose load yet see prices climb; SP-15 grows load and peaks with prices below a high 2023 base. MISO’s 2026 load is estimated.
MISO (est.) +4.0% +4.9% +65.8% +26.8% NEPOOL +0.1% +0.1% +49.5% +53.8%
Same measures year-to-date (Jan–Oct 2023 → Jan–Oct 2026): weather-normalized load from a Jan–Oct regression on CDD, HDD, month and year effects; peak load and prices are Jan–Oct averages. Year-to-date, PJM shows the clearest load-and-price rise; ERCOT and SP-15 prices sit below a scarcity-heavy 2023.
Summary comment by ISO
▪ PJM-W — load up, price up: the clean thesis
– Weather-normalized load +8.3% (2023→26), +2.4% in the last year; peak +6.5%.
– DA price +83%, RT +70%; Oct 13 RT peak $1,770 in the maintenance-window squeeze.
– October’s largest drag (-1.88 pts) on a −5.6% excess leg as its winter months repriced lower.
▪ ERCOT-N — fastest load growth, prices recovering
– WN load +17.7% (fastest of the six), peak +20.4%.
– DA+9%,RT+11%vsOctober2023;DAbyyear$32→$25→$31→$35.
– Wind, solar and storage still cap scarcity in the shoulder months; a -0.65-pt contributor (−3.9% leg).
▪ MISO — estimated 2026 load; prices sharply higher
– 2026 load estimated from PJM-RTO load and Chicago CDD/HDD (Aug–Oct feed blank): est. WN load +4.0%, peak +4.9% —
indicative only.
– DA +66%, RT +27% — measured, not estimated; Indiana Hub RT peaks $1,042 (Oct 13) and $1,074 (Oct 18). – A -0.70-pt contributor on a −2.4% excess leg return.
▪ NYISO-G — load lower, prices higher
– WN average load −3.4%, peak −1.6%.
– DA +57%, RT +42% vs 2023 (slightly lower than 2025): gas, capacity and NYC-zone congestion drive price, not average
demand; RT $974 on Oct 16.
– A small drag this month (-0.16 pts).
▪ NEPOOL — flat load, pricier energy
– WN average load +0.1%, peak +0.1%; Boston heating demand −52 HDD vs normal. – DA +50%, RT +54% on gas dependence and winter-reliability premia.
– The smallest drag this month (-0.06 pts).
▪ SP-15 — record October heat, load and peaks up
– WN load +7.4%, peak +11.9%; Los Angeles +143 CDD vs normal.
– DA −13% vs a high 2023 base but +51% on a year ago ($31 → $47); the midday solar glut still caps most hours. – Spot heat did not hold in the forwards: a −4.9% leg, -0.47 pts.
Method: per-ISO OLS on daily October data, Load = a + b·CDD + c·HDD + year effects; weather-normalized load = fitted load at the common (4-year mean) October CDD and HDD. From October the model adds heating degree-days for the shoulder and winter months; in summer HDD ≈ 0 and it reduces to the prior CDD-only model. One representative city per ISO (Open-Meteo ERA5, CC BY 4.0). Load is ISO-total (e.g., PJM-RTO); price is the index hub. A linear degree-day response is a simplification. MISO’s Aug–Oct 2026 load feed is blank in the workbook; its 2026 daily load is estimated from PJM-RTO load and Chicago CDD and HDD with month and year effects (OLS on all 2023–26 days with both series, R2 0.89, RMSE ≈3.2 GW), so MISO 2026 load figures are indicative only. Prices are measured.
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
ISO (Oct ’26)
WN Load Δ
Peak Δ
DA Price Δ
RT Price Δ
PJM-W
+8.3%
+6.5%
+83.3%
+70.2%
ERCOT-N
+17.7%
+20.4%
+9.4%
+11.4%
NYISO-G
−3.4%
−1.6%
+57.0%
+42.2%
SP-15
+7.4%
+11.9%
−13.0%
−12.2%
ISO (YTD ’26)
WN Load Δ
Peak Δ
DA Price Δ
RT Price Δ
PJM-W
+8.2%
+10.3%
+122.6%
+128.1%
ERCOT-N
+13.6%
+13.2%
−43.1%
−38.6%
MISO (est.)
+4.8%
+5.3%
+65.6%
+71.6%
NYISO-G
−1.6%
+3.3%
+110.6%
+100.0%
NEPOOL
+1.4%
+4.8%
+90.9%
+89.8%
SP-15
+4.2%
+5.7%
−53.1%
−53.4%
ICEUPWRT · Appendix · October 31, 2026 Appendix · Per-ISO Term Structure
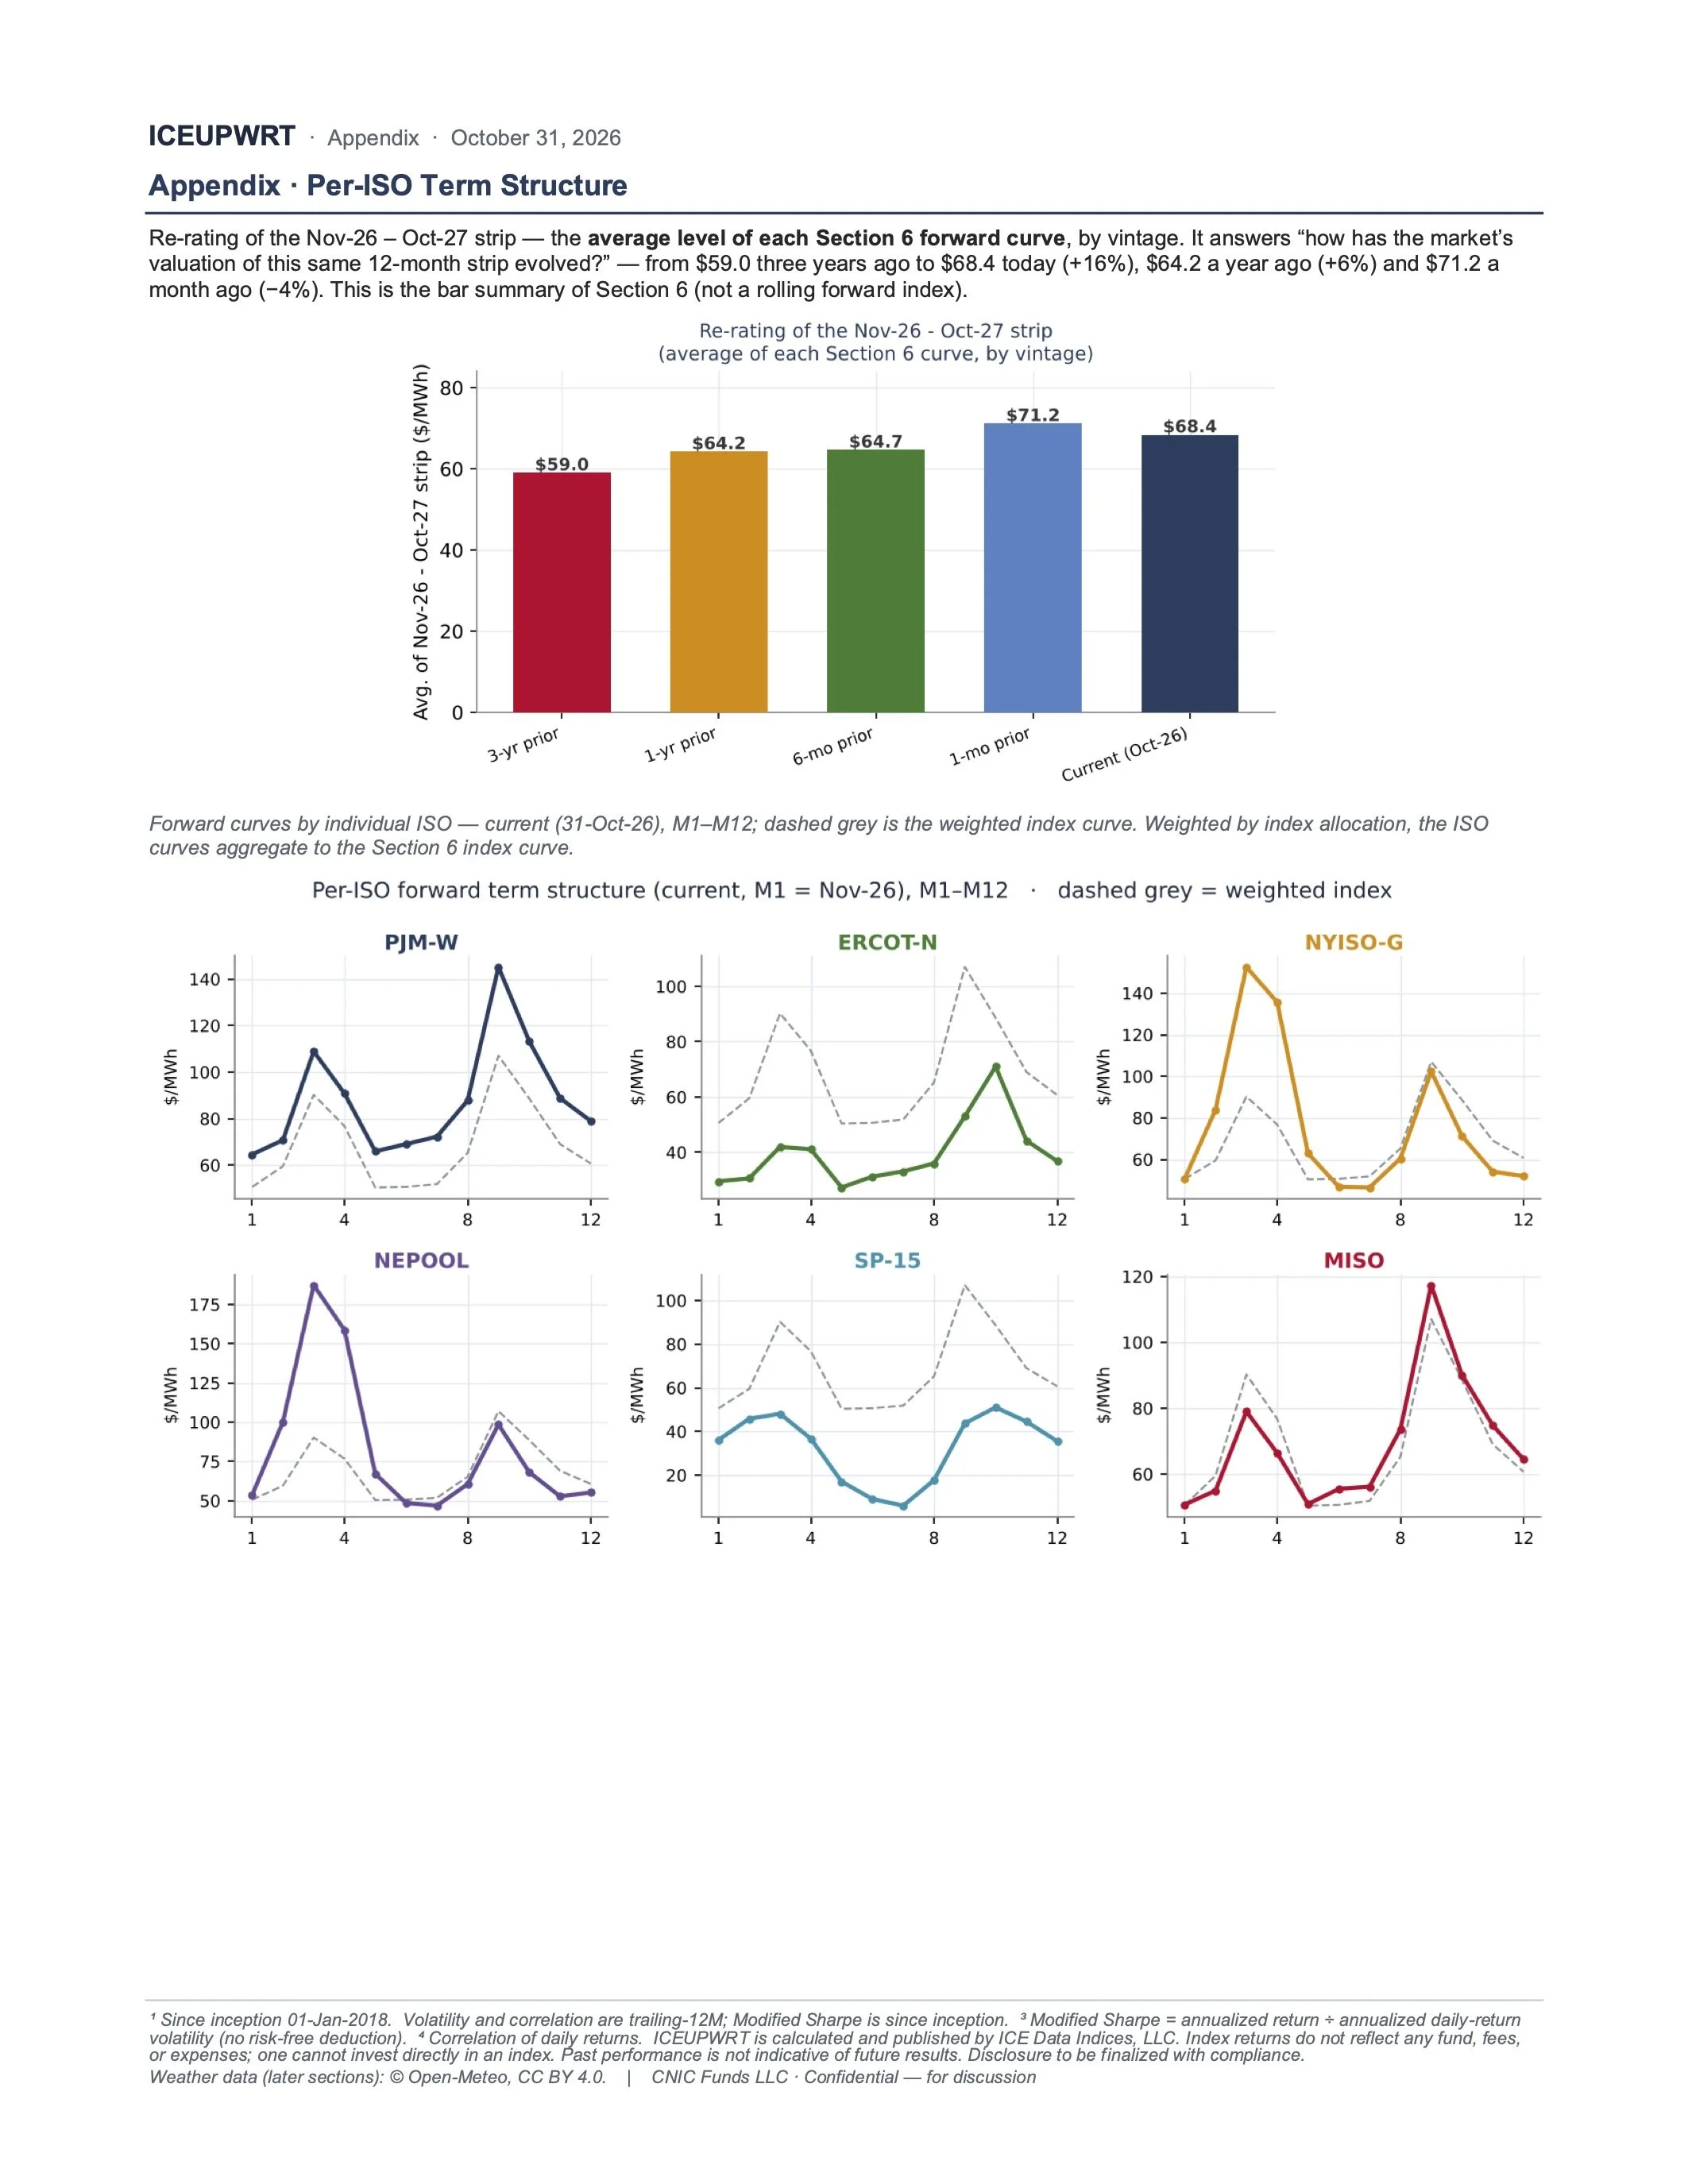
Re-rating of the Nov-26 – Oct-27 strip — the average level of each Section 6 forward curve, by vintage. It answers “how has the market’s valuation of this same 12-month strip evolved?” — from $59.0 three years ago to $68.4 today (+16%), $64.2 a year ago (+6%) and $71.2 a month ago (−4%). This is the bar summary of Section 6 (not a rolling forward index).
Forward curves by individual ISO — current (31-Oct-26), M1–M12; dashed grey is the weighted index curve. Weighted by index allocation, the ISO curves aggregate to the Section 6 index curve.
1 Since inception 01-Jan-2018. Volatility and correlation are trailing-12M; Modified Sharpe is since inception. 3 Modified Sharpe = annualized return ÷ annualized daily-return volatility (no risk-free deduction). 4 Correlation of daily returns. ICEUPWRT is calculated and published by ICE Data Indices, LLC. Index returns do not reflect any fund, fees, or expenses; one cannot invest directly in an index. Past performance is not indicative of future results. Disclosure to be finalized with compliance.
Weather data (later sections): © Open-Meteo, CC BY 4.0. | CNIC Funds LLC · Confidential — for discussion
